


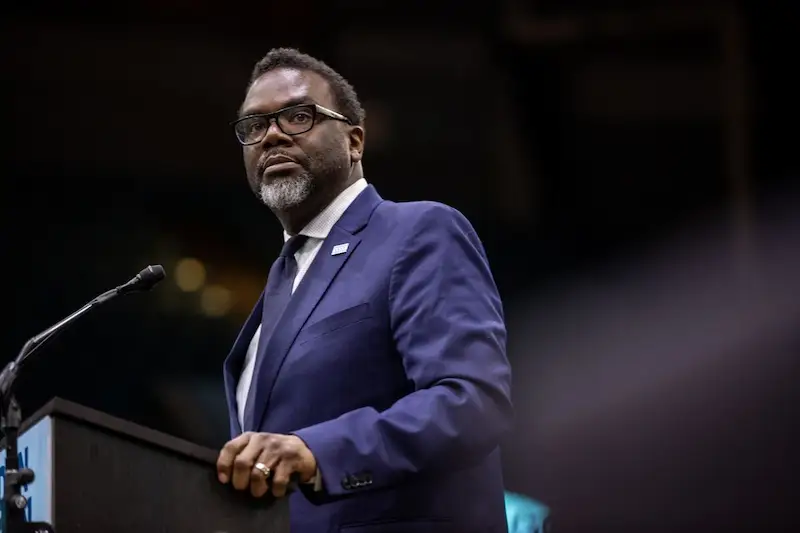


Shortly after taking office as Chicago's mayor, Brandon Johnson made it a priority to address the city's massive pension problem. With over $35 billion owed to its pension funds, Chicago's financial burden threatens not only its own recovery but also the mayor's ambitious agenda. While the city faces challenges such as rising crime rates, pandemic-related inequalities, and corporate departures, the pension gap remains a pressing issue that requires urgent attention. This predicament serves as a cautionary tale for other municipalities across the United States grappling with funding shortfalls and neglected contributions.
Johnson managed to temporarily alleviate the crisis by convincing state lawmakers to postpone legislation that would have added billions to the pension debt. Instead, he established a working group composed of city officials, legislators, union representatives, and pension experts to devise solutions by October. However, the task at hand is far from easy due to the multitude of competing interests. Johnson, who received support from labor groups during his campaign, needs to find a solution that satisfies various priorities, while also considering constitutional protections for pension benefits.
Raising new revenue seems like the most viable option, as Johnson initially proposed a tax plan to generate $800 million through levies on big businesses, airlines, and the wealthy. However, gaining support from both his transition committee and state lawmakers may prove challenging. Increasing property taxes is another possibility, but it would undoubtedly face significant backlash. During his campaign, Johnson promised not to raise property taxes, and many Chicagoans are already frustrated by recent substantial increases in these levies.
Notwithstanding, avoiding property tax hikes could potentially erode investors' confidence in Chicago's municipal bonds. Moody's Investors Service upgraded the city's rating in November, which was significant progress since Chicago had been plagued by junk ratings since 2015. Molly Shellhorn of Nuveen, the largest holder of Chicago's debt, argues that neglecting property taxes has contributed to the pension funding crisis, making it unwise to discard this stable revenue source.
While finding new revenue streams to allocate more funds to the pension system is crucial, it also limits Johnson's ability to finance other key policy initiatives, such as bolstering homeless services, violence prevention efforts, and youth employment programs. Balancing the needs of the pension system with the demands of the city's citizens adds complexity to the already challenging task of stabilizing Chicago's financial future.
Chicago currently spends a significant portion of its budget on pension payments, with about 20% of its expenditures allocated to pensions and over 80% of property tax dollars going toward retirement payouts. The annual payments towards the city's four pension systems for retired firefighters, police officers, municipal office workers, and laborers reached a peak of $2.6 billion this year and are projected to total $2.4 billion in 2024.
While bankruptcy is not an option for Chicago due to state law, the city's financial situation remains dire. In 2015, the state supreme court ruled against cost-cutting measures, leading to Moody's downgrading the city's rating to junk. However, the city managed to improve its position by making actuarially calculated contributions to all four pension funds, resulting in the elimination of its junk rating.
Lori Lightfoot, Johnson's predecessor, allocated a projected surplus of $698 million from 2022 and 2023 towards reducing the pension liability until revenue from the city's first casino becomes available in 2026. However, these surpluses are expected to diminish as the last of the federal aid from the American Rescue Plan Act is depleted this year.
State Representative Kelly Burke, a member of Johnson's working group, acknowledged the immense challenge of addressing rising costs and improving the funding levels of the four pension funds. It is clear that finding innovative solutions and generating new sources of revenue is imperative to restore the fiscal health of Chicago and ensure a stable future for its residents.